What does underinsured motorist coverage mean in the legal space?

What does underinsured motorist coverage mean in the legal space?

In the Legal space, “underinsured motorist coverage” (UIM) refers to a type of insurance that provides protection for drivers who are involved in accidents with motorists whose insurance coverage is insufficient to fully cover the damages. According to the Munley Law Glossary, this coverage is designed to fill the gap between the at-fault driver’s insurance limits and the actual damages sustained by the injured party.

Understanding Underinsured Motorist Coverage

Underinsured motorist coverage involves several key aspects:

Purpose: The primary purpose of UIM coverage is to protect drivers when they are in an accident with a motorist who has insurance but whose coverage limits are too low to cover the full extent of the damages. This can help ensure that victims receive adequate compensation for their injuries and losses.

Coverage Limits: UIM coverage has its own limits, which are typically specified in the insurance policy. These limits represent the maximum amount that the insurer will pay for damages caused by an underinsured motorist.

Excess Coverage: UIM coverage applies when the damages exceed the amount covered by the at-fault driver’s insurance. For example, if the at-fault driver has a $25,000 insurance limit but the damages amount to $50,000, UIM coverage can help cover the remaining $25,000.

State Requirements: The availability and requirements for underinsured motorist coverage vary by state. Some states require drivers to carry UIM coverage, while others allow it as an optional add-on to auto insurance policies.

Legal Contexts Where Underinsured Motorist Coverage Applies

Automobile Accidents: UIM coverage is most commonly used in automobile accident cases where the at-fault driver does not have sufficient insurance to cover the injured party’s medical expenses, property damage, or other losses.

Personal Injury Claims: In personal injury claims involving automobile accidents, UIM coverage can provide additional compensation when the at-fault driver’s insurance is inadequate. This can help cover medical bills, lost wages, pain and suffering, and other damages.

Insurance Disputes: Disputes may arise over UIM coverage, such as disagreements about the amount of coverage or whether the at-fault driver was underinsured. In such cases, legal Action may be necessary to resolve the issue and obtain the appropriate compensation.

Policy Limits: The specifics of UIM coverage, including policy limits and exclusions, are outlined in the insurance policy. Understanding these details is crucial for effectively utilizing UIM coverage and ensuring adequate protection.

Legal Implications of Underinsured Motorist Coverage

Supplementary Coverage: UIM coverage serves as supplementary insurance that provides additional protection when other insurance limits are insufficient. It helps bridge the gap between what is covered by the at-fault driver’s insurance and the actual damages incurred.

Claim Process: To make a claim under UIM coverage, the policyholder must typically demonstrate that the at-fault driver was underinsured and provide documentation of the damages. The insurance company will then evaluate the claim and determine the amount of compensation.

Policy Limits and Excess Coverage: The amount of compensation available under UIM coverage is subject to the policy limits. If the damages exceed these limits, additional sources of compensation may need to be pursued.

State Variations: Legal requirements and regulations related to UIM coverage vary by state. Drivers should be aware of their state’s requirements and ensure they have adequate coverage as part of their auto insurance policy.

Role of Munley Law Glossary

The Munley Law Glossary provides definitions and explanations of legal terms related to underinsured motorist coverage, helping clients, attorneys, and other stakeholders understand the concept and its applications in insurance and legal contexts.

In the legal space, “underinsured motorist coverage” (UIM) is insurance that provides additional protection when involved in an accident with a driver whose insurance is insufficient to cover the damages. UIM coverage helps bridge the gap between the at-fault driver’s insurance limits and the actual damages, ensuring that victims receive adequate compensation. Understanding UIM coverage, as detailed in the Munley Law Glossary, is crucial for managing risks, filing claims, and securing proper protection in automobile accidents.
What are Digital Credentials?

Digital credentials represent the advancement from traditional paper-based certificates. Without needing to have it mailed, it acknowledges academic achievements, event participation, or training completion. As education increasingly shifts to online platforms, the recognition of verifiable credentials must adapt accordingly.

Online educators – CE providers, personal coaches, mentors, and more- sought to make online learning a more valuable experience with these rewards.

Digital credentials serve as the solution. It enables online educators to efficiently create, distribute, and record credentials while ensuring students automatically receive them, streamlining the learning procedure.

Digital Certificates: Online Credentials on a Certificate

Paper certificates signify proof that learners have acquired the skills they have studied for. Digital certificates are proof that can be sent online without fuss. These online credentials can be duplicated if their printed versions are lost or damaged. Furthermore, they can be easily accessed through a digital storage device for hard-copy purposes and reference.

How Digital Certificates Help Online Educators

  • Saves Time and money by Freeing the Menial Tasks of Paper Certificate Management
  • Add Value and Credibility to Your online Educational Programs and Encourage Increased Enrollment
  • Secure Digital Storage to Avoid Physical Loss and Damage

How Digital Certificates Help Their Students

  • Portable and Accessible from Storage Devices and Safe Online Servers
  • Shareable in Professional Media Profiles for Self-Promotion of Expertise and Competency
  • Increase Chances of Getting Hired by Having Certified Skills

Everyone Benefits from the advantages digital certificates bring. So, how can educators incorporate it into their digital platforms? Simple, you don’t even need to know how to code.

SimpleCert®: Your Digital Certificate Management

Online educators sometimes use various independent tools to create their students’ learning experiences. SimpleCert® puts all the certificate tools you need on one platform. See our platform features below.

SimpleCert®’s certificate maker lets you create your digital certificate faithful to your brand with its intuitive drag-and-drop system and free professional templates.

Say goodbye to manual mail merge. SimpleCert® personalizes certificates and emails in thousands when you directly upload recipient data via Excel or CSV file.

All certificates are stored in a secure cloud server. By subscribing to a monthly SimpleCert® plan, every recipient gains entry to their personalized recipient portal.

Automate Digital Certificates on Your Platform

When educators create webinars, modules, and video lessons, they can make a more professional experience for their learners by having them automatically receive their digital credentials once they have finished them. This is possible by integrating their SimpleCert® account with their trusted platforms.

“We use SimpleCert® to automatically send training certifications to our customers. It is easy to use and our customers receive their certifications rapidly. This Certificate Management System increases our productivity and our customers’ satisfaction!”

Véronique Trépanier-Boulay

Executive Director, FORMobile

Ensure Your Student’s Professional Experience with Your Platform and Marketing

Many educators rely on multiple tools to enhance their students’ learning journey. Yet, some tools tend to advertise on the educators’ platforms and email marketing, disrupting the professional experience for students.

Here at SimpleCert®, it’s all about you as their educator.

We prioritize streamlining your certification system without any intrusive self-promotion. Our aim is to optimize your certification process for both you and your students.

Design Your Digital Credentials Today!

Tailor and share professional digital certificates effortlessly. Sign up for a complimentary SimpleCert® account – no credit card needed! With your free account, generate and distribute up to 10 certificates monthly. Elevate your online educational programs by leveraging SimpleCert® to oversee your certification workflow.

SimpleCert | What are Digital Credentials?

Premium Pool Cover in South Africa | Order Now

cover for pools, cover of swimming pool, pool cover, pool covers, pools with cover, cover for a pool, cover for a swimming pool, cover for swimming pool, cover for the pool, pool cover cover, pool with cover, covers for pools, covers for pool

With the sun-drenched landscapes of South Africa as a perfect backdrop for pristine swimming pools, the essentiality of a pool cover becomes not just a luxury but a necessity. That’s where Designer Pool Covers enters the scene, standing as a beacon among pool cover specialists in the region. Offering an inclusive line-up of swimming pool covers, from the essential safety pool cover to innovative Solar pool covers, this company ensures that every swimming pool is an oasis of safety and efficiency.

Discover the Variety of Premium Pool Cover Offerings from Designer Pool Covers

Designer Pool Covers, a leading name in bespoke pool protection, offers a robust lineup of pool cover solutions that caters to a variety of needs for pool owners across South Africa. They have perfected the art of combining practicality with luxury, offering items such as automatic pool covers known for their convenience and high-end mechanism, ensuring pools are safeguarded effortlessly and in style.

Among their diverse offerings, the Pool cover represents the pinnacle of automated pool protection, while the solar pool covers, such as the Ultra Dome and Aqua-Bubble, are designed to maintain a warm and debris-free pool. There’s no overlooking the ingenuity of the winter pool cover options like the Leaf Catcha and Aqua-Guard, which provide optimized seasonal utility and maintenance.

The safety pool cover is an exemplary product for those prioritizing Security and peace of mind, fabricated with durability and resilience to protect against unwanted access and Environmental elements. To complement these coverings, Designer Pool Covers also offers convenient pool cover reels, facilitating easy deployment and storage of coverings. In addition, the critical pool cover pump stands as an essential accessory for maintaining optimal pool condition, efficiently managing excess water and ensuring prolonged cover longevity.

Below is a comparative illustration of the various pool cover options and their features, reflecting Designer Pool Covers’ commitment to innovation and customer satisfaction:

Cover Type Key Feature Seasonal Use Energy Conservation Safety Index Additional Accessories
Automatic Pool Cover One-touch operation All-season High Top-tier Pool cover pump, pool cover reel
Solar Pool Cover Heat retention Primarily for colder months Excellent Moderate N/A
Winter Pool Cover Debris protection Winter Good High Pool cover pump
Safety Pool Cover Child and pet protection All-season Moderate Maximum N/A

Endeavoring to address every nuanced requirement of pool ownership, Designer Pool Covers demonstrates exceptional customer service, swift installation, and a vast selection that promises efficiency, security, and a pristine pool environment. Catered to both residential and commercial clients, their offerings are a testament to their mission — creating a safe, energy-efficient, and well-maintained aquatic oasis for everyone to enjoy.

Maximize Your Pool’s Potential with a Pool Cover Throughout the Seasons

Throughout the shifting seasons, pool owners in South Africa face various challenges to maintain optimal pool conditions. Designer Pool Covers provides a gamut of covers that facilitate swimming pool maintenance, enabling homeowners to secure and utilize their swimming oasis year-round. Leveraging covers effectively not only maintains pool water temperature but also ensures swimming pool safety and efficiency, regardless of the weather patterns.

Automatic Pool Covers for Convenience and Efficiency

With the modern pace of life, convenience is key, and this is where Designer Pool Covers’ automatic pool cover shines. It caters to the need for convenient pool maintenance with its one-touch operation, allowing swift deployment and retraction. This pool cover efficiency is paired with accessories such as roll-up stations and pool cover pumps, advancing a smooth methodology to cover management while contributing to energy conservation and cost savings—a testament to the blend of innovation and ease that a premium pool cover can offer.

more info: https://www.designercovers.co.za/

Unraveling the Mystery: What Is Commercial Property Insurance?

Defining Commercial Property Insurance

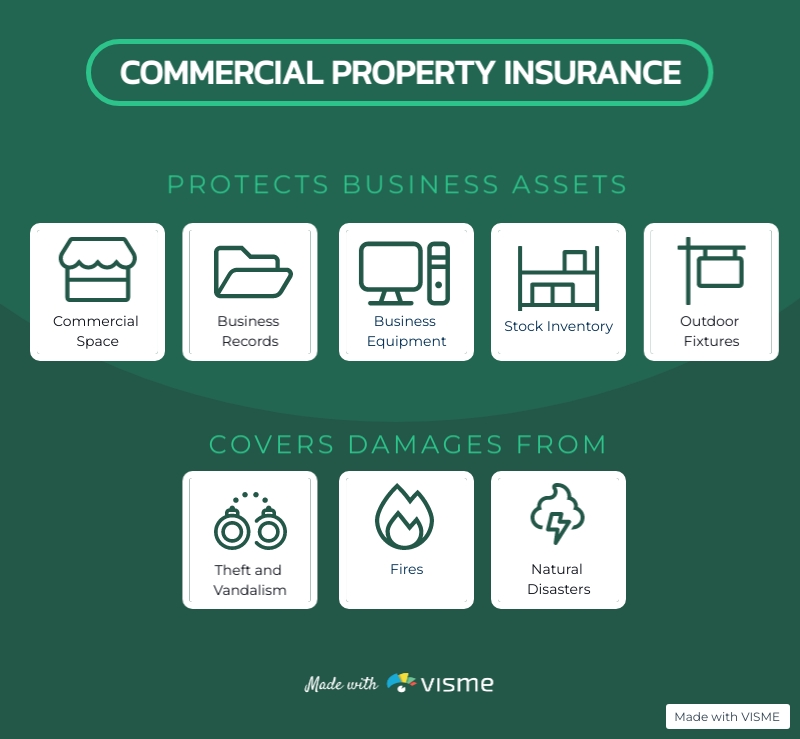
Commercial or business property insurance is a vital insurance policy for businesses, safeguarding a company’s real estate and onsite physical assets. This coverage protects against unforeseen incidents, including fire, theft, and natural disasters. It’s similar to property insurance, but business owners can deduct their premiums as expenses.

What Does Commercial Property Insurance Cover? 


Types of Commercial Property Insurance by Policy

The policy type plays a significant role in determining the scope of coverage for your commercial space and equipment:

  1. Named Perils Policy: This policy explicitly covers incidents listed in the policy, such as theft and fire. Business owners can tailor coverage based on their unique risk profile.
  2. Open Perils Policy: Offering broader coverage, an Open Perils Policy protects against a wide range of incidents but comes with a list of exclusions, such as flood damage. While providing more extensive protection, this policy generally costs more.

What Does Commercial Property Insurance NOT Cover?

While commercial property insurance provides robust coverage for various incidents, it’s crucial to note the scenarios that fall outside its scope. This type of insurance does not cover incidents related to tenants using their commercial space and equipment. Expressly, it excludes:

  • Company cars getting into an accident during work hours, which your commercial auto insurance covers,
  • Flood damages, which require separate insurance coverage,
  • Damages to your client or customer’s property within your commercial space and
  • Incidents where you or your employees accidentally or intentionally damage the commercial space and physical assets at work.

Do I Need Commercial Property Insurance?

For business owners with commercial spaces, having an official agreement with the building’s owner is common. This outlines damages for which the business owner is responsible. Commercial property insurance serves as a financial safety net, covering costs instead of requiring out-of-pocket payments for repairs. It becomes crucial during severe cases like natural disasters or significant fires, preventing business closure and mitigating financial burdens. Home business owners should opt for home business insurance instead.

How Much Does Commercial Property Insurance Cost?

The cost of commercial property insurance varies for small businesses, with an average monthly premium of $67, according to Insureon. Notably, 62% of small businesses spend $100 or less for coverage.

Several factors contribute to the cost of commercial property insurance, including:

  • Value of Business Assets: The higher the value of physical assets within the commercial property, the higher the replacement value and coverage level, influencing the insurance cost.
  • Weather Conditions of the Location: Buildings in areas with a higher risk of weather-related catastrophes may incur higher coverage costs due to increased risk.
  • Access to Fire Protection: The presence or absence of fire department services in the vicinity can impact insurance quotes, with higher costs for properties outside city fire protection zones.
  • Building Safety Measures: Investing in safety measures like fire alarms and security systems can lower insurance costs.
  • Material of the Building: Buildings constructed with fire-proof materials may qualify for lower rates, but additional combustible structures could negate the reduction of rates.
  • Occupancy: The nature of the business in the commercial space also influences premiums. Businesses with a higher risk of incidents, such as restaurants or welding shops, may experience higher premiums.
  • Other factors: Payroll size, number of employees, and claims history. 

What Coverage Limit Should I Choose per Occurrence?

Choosing the right coverage limit per occurrence is crucial for your specific business needs. Discussing with your insurance agent helps make an informed decision on the necessary coverage amount.

For example, if your business suffers $500, 000 in wind damages but your maximum coverage is $400, 000 per incident, you’ll face a $100, 000 shortfall. Aligning coverage limits with potential risks is key to avoiding unexpected out-of-pocket expenses.

Collaborating with your insurance agent ensures you determine the most suitable coverage limits for financial security in unforeseen incidents.

What is the Commercial Property Insurance’s Standard Deductible?

The standard deductible for a commercial property insurance policy can vary, typically ranging from hundreds to more than a thousand dollars. According to Insureon, the average deductible chosen by their customers is $1, 000.

understanding the standard deductible is crucial as it represents the amount a business owner needs to contribute out of pocket before the insurance coverage takes effect. The higher the deductible you pay, the lower your insurance cost will be.

Types of Commercial Property Insurance

Commercial property insurance comes in different forms, offering varying coverage approaches to meet the diverse needs of businesses. Two primary types include:

  • Replacement Cost Coverage: With this type of coverage, the insurance company commits to replacing your commercial property with similar, new items. These items are typically non-tax-deductible.
  • Actual Cash Value Coverage: Under this coverage, damaged property is reimbursed based on its fair market value, considering depreciation. While providing coverage for the current property value, it factors in depreciation, influencing the reimbursement amount.

Business Owner’s Policy (BOP)

For small businesses, a Business Owner’s Policy (BOP) is a practical and cost-effective choice. It bundles essential insurance policies, including Commercial Property Insurance, General Liability Insurance, and Business Interruption Insurance, offering comprehensive coverage at an affordable rate. This streamlined approach helps optimize risk management strategies for small businesses.

Commercial Property Insurance for Your Business

Commercial property insurance serves as a crucial safety net for businesses, offering protection in times of emergency, including natural disasters, fire, or theft. This insurance ensures business continuity by covering damages to your commercial space and physical assets, allowing you to focus on your operations without the financial burden of repairs or replacements.

The costs of commercial property insurance are influenced by various factors, including the value of your business location, the building structure, and the type of business you operate. Click below to learn more. 

Goodale & Barbieri